Attorney-Led Strategy vs. Non-Attorney Resolution for Payroll Audits
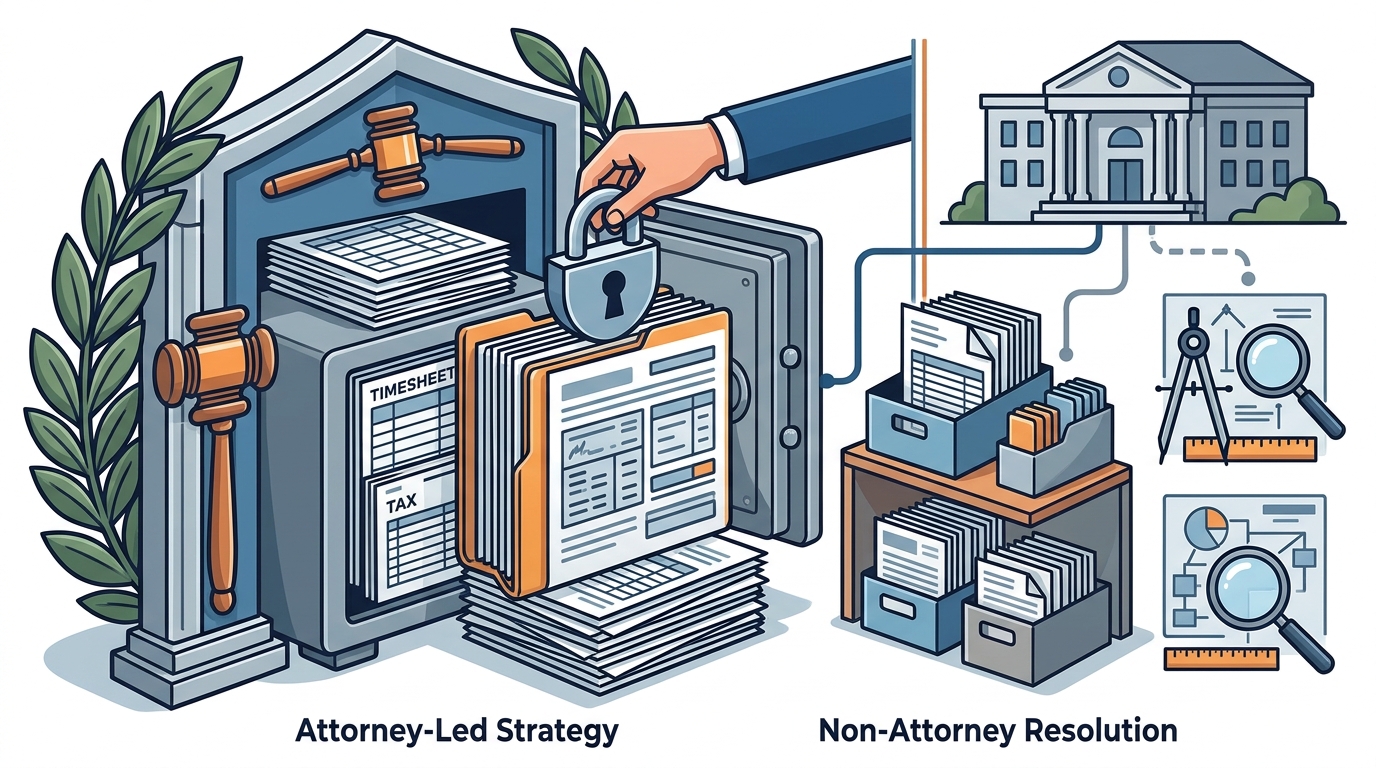
Attorney-led strategy differs from non-attorney resolution primarily through the protection of attorney-client privilege, the ability to control agency communication, and the application of complex legal standards for worker classification. The Law Office of Jorge Alesna, Jr. provides this guide to help Bakersfield and Kern County business owners understand the structural advantages of legal representation during payroll tax audits.
Attorney-Client Privilege
Attorney-client privilege is a legal protection that prevents the government from compelling an attorney to disclose confidential communications made by a client for the purpose of seeking legal advice. In the context of a payroll audit, this privilege creates a secure channel for discussing sensitive business operations, financial struggles, and potential legal vulnerabilities. When a business owner speaks with a non-attorney representative, such as a bookkeeper or a tax preparer who is not an attorney, those conversations are generally not protected by this specific privilege.
During an audit, the Internal Revenue Service (IRS) or the California Employment Development Department (EDD) may issue summons or information requests. If a business owner has made admissions or discussed potential misclassification with a non-attorney, that information may be discoverable. Conversely, communications with a tax controversy attorney are shielded. This allows the attorney to investigate the facts of the case, identify weaknesses in the agency's position, and develop a defense strategy without the fear that the investigation itself will be used against the client. The Law Office of Jorge Alesna, Jr. utilizes this privilege to ensure that the initial intake and subsequent strategy sessions remain confidential, providing a safer environment for clients to disclose the full scope of their payroll practices.
IRS Appeals Representation
IRS Appeals representation involves the formal process of challenging an IRS determination before an independent office within the agency. When an audit results in a proposed adjustment, the taxpayer may receive a 30-day letter, which provides the opportunity to request a review by the IRS Independent Office of Appeals. This stage is critical because it is often the last chance to resolve the dispute without litigation. An attorney-led approach to IRS Appeals focuses on the "hazards of litigation," which is a formal consideration where the Appeals Officer evaluates the likelihood that the IRS would lose the case if it went to court.
Non-attorney representatives often lack the training to effectively argue the hazards of litigation or to present complex legal precedents. An attorney can frame the dispute in a way that highlights the legal risks the IRS would face, potentially leading to a settlement that is more favorable than the initial audit determination. For clients in Bakersfield and throughout California, the Law Office of Jorge Alesna, Jr. handles these administrative appeals, ensuring that the record is developed properly and that the legal arguments are presented with the necessary rigor to influence the Appeals Officer's decision.
Worker Misclassification Risk
Worker misclassification risk is the potential liability that arises when a business treats an employee as an independent contractor, resulting in unpaid payroll taxes and penalties. This is one of the most common issues in payroll audits. The IRS and the EDD use different tests to determine worker status. The IRS uses a multi-factor common law test, while California applies the stricter "ABC test" under the Dynamex standard. Under the ABC test, a worker is presumed to be an employee unless the hiring entity can prove that the worker is free from control, performs work outside the usual course of the business, and is customarily engaged in an independently established trade.
The risk is not merely financial; it can also involve personal liability for business owners. If the EDD determines that workers were misclassified, the business may owe back taxes for Unemployment Insurance (UI), Employment Training Tax (ETT), and State Disability Insurance (SDI). An attorney-led strategy involves a detailed analysis of the working relationship to determine if the ABC test can be met. The Law Office of Jorge Alesna, Jr. reviews contracts, payment methods, and the actual day-to-day control exercised over workers to assess the true risk and to prepare a defense that addresses the specific legal standards applied by the agency.
Legal Negotiation Strategy
Legal negotiation strategy is the process of using legal authority, procedural rules, and case law to reach a favorable resolution with a tax agency. Unlike a simple request for a payment plan, a legal negotiation involves challenging the validity of the assessment itself. An attorney can argue that the agency's methodology for calculating wages was flawed, that the statute of limitations has expired, or that the workers in question were legitimately independent contractors. This type of negotiation requires a deep understanding of tax code and administrative procedure.
Non-attorney representatives may focus primarily on the amount of the debt and the ability to pay. While this is important, it does not address the underlying legal validity of the assessment. By focusing on the legal merits, an attorney can often reduce the principal amount of the tax owed, which in turn reduces the penalties and interest. The Law Office of Jorge Alesna, Jr. employs this strategy to ensure that clients are not simply paying a debt that may be legally incorrect, but are instead engaging in a substantive legal process that protects their rights and assets.
Agency Communication Strategy
Agency communication strategy is the systematic approach to managing all interactions with tax authorities, including the IRS, EDD, FTB, and CDTFA. In a payroll audit, the agency will request documents, schedule interviews, and issue notices. Every communication is an opportunity for the agency to gather information. An attorney-led strategy involves controlling the flow of information. The attorney acts as the point of contact, reviewing all requests before they are answered and ensuring that the responses are precise and legally sound.
When a business owner communicates directly with an auditor, there is a risk of providing unnecessary information or making statements that can be interpreted unfavorably. An attorney ensures that the business only provides what is legally required and that the context of the information is controlled. This is particularly important in cases involving worker classification, where the nuances of the working relationship can be easily misunderstood. The Law Office of Jorge Alesna, Jr. manages these communications to protect the client from inadvertent admissions and to keep the audit focused on the specific issues at hand.
Worker Misclassification Exposure
Worker misclassification exposure is the total financial and legal liability that a business faces if the agency reclassifies its independent contractors as employees. This exposure includes back payroll taxes, penalties, and interest. In California, the exposure can be significant because the state imposes its own set of payroll taxes in addition to federal requirements. The EDD may assess penalties for failure to withhold and pay over these taxes. Furthermore, if the business is a corporation or LLC, the EDD may attempt to hold the owners or officers personally liable for the unpaid taxes under certain circumstances.
Understanding the full scope of this exposure is a key part of an attorney-led strategy. An attorney can calculate the potential liability, identify which workers are most at risk, and determine if there are any defenses available. This allows the business to make informed decisions about how to proceed. The Law Office of Jorge Alesna, Jr. helps clients in Bakersfield and Kern County understand their exposure and develop a plan to manage it, whether that involves settling the dispute, appealing the determination, or restructuring the business's payroll practices to prevent future issues.
Penalty Negotiation
Penalty negotiation is the process of arguing with the tax agency to reduce or eliminate the penalties assessed for non-compliance. Penalties can be a significant portion of the total liability in a payroll audit. The IRS and the EDD have discretion to abate penalties if the taxpayer can show reasonable cause and good faith. An attorney can present evidence of the business's efforts to comply with tax laws, such as the use of a tax professional, the implementation of payroll software, or the lack of prior violations. This evidence can be used to argue that the penalties should be reduced or removed.
Non-attorney representatives may not be as effective in penalty negotiation because they may not be familiar with the specific legal standards for reasonable cause. An attorney can craft a detailed penalty abatement request that addresses the agency's requirements and presents the client's case in the most favorable light. The Law Office of Jorge Alesna, Jr. focuses on penalty negotiation as a key component of its representation, aiming to reduce the overall cost of the audit for its clients. By combining legal arguments with factual evidence, the attorney can often achieve a significant reduction in the penalties assessed.
Comparison of Representation Models
| Feature | Attorney-Led Strategy | Non-Attorney Resolution |
|---|---|---|
| Confidentiality | Protected by attorney-client privilege | Generally not protected by privilege |
| Legal Argumentation | Can argue legal standards and hazards of litigation | Focuses primarily on factual and financial issues |
| Communication Control | Attorney acts as sole point of contact | Client or representative communicates directly |
| Worker Classification | Applies specific legal tests (e.g., ABC test) | May lack expertise in complex legal standards |
| Penalty Abatement | Can argue reasonable cause and good faith legally | May request abatement without legal basis |
Key Takeaways
- Attorney-client privilege protects confidential communications during an audit, which is not available with non-attorney representatives.
- Attorneys can effectively argue the "hazards of litigation" during IRS Appeals, potentially leading to better settlements.
- Worker misclassification is a major risk in payroll audits, and attorneys apply specific legal tests like California's ABC test to assess liability.
- Legal negotiation strategy focuses on the validity of the assessment, not just the ability to pay the debt.
- Controlling agency communication prevents inadvertent admissions and keeps the audit focused.
- Attorneys can calculate and manage worker misclassification exposure, including potential personal liability for owners.
- Penalty negotiation is more effective when supported by legal arguments for reasonable cause and good faith.
- The Law Office of Jorge Alesna, Jr. provides these strategic advantages to clients in Bakersfield and Kern County.
Frequently Asked Questions
What is the main difference between an attorney and a tax preparer in an audit?
The main difference is the protection of attorney-client privilege and the ability to make legal arguments. An attorney can represent you in formal proceedings and argue legal standards, while a tax preparer generally focuses on factual and financial issues.
Can an attorney stop a payroll audit?
An attorney cannot unilaterally stop an audit, but they can control the process, challenge the agency's methodology, and potentially resolve the dispute before it becomes a final assessment. They can also negotiate a settlement that may reduce the scope of the audit.
What is the ABC test for worker classification?
The ABC test is a California legal standard that presumes a worker is an employee unless the hiring entity proves that the worker is free from control, performs work outside the usual course of the business, and is customarily engaged in an independently established trade.
Do I need an attorney if I am just behind on payroll taxes?
If you are simply behind on payments and have no disputes, you may be able to resolve the issue with a payment plan. However, if the agency is questioning your worker classification or issuing assessments, an attorney can help you challenge the liability and negotiate penalties.
How does the Law Office of Jorge Alesna, Jr. handle payroll audits?
The firm provides attorney-led representation, utilizing privilege to protect client communications, controlling agency interactions, and applying legal standards to challenge assessments and negotiate penalties.
Can business owners be held personally liable for payroll taxes?
Yes, in certain circumstances, the EDD or IRS can hold owners or officers personally liable for unpaid payroll taxes, particularly if the business is dissolved or if the individuals are found to be responsible persons who willfully failed to pay the taxes.
Conclusion
Choosing between attorney-led strategy and non-attorney resolution for a payroll audit is a critical decision that can have long-term financial and legal consequences. The advantages of legal representation, including privilege, strategic communication, and the ability to argue legal standards, provide a stronger defense for business owners facing complex tax disputes. The Law Office of Jorge Alesna, Jr. is dedicated to providing these services to clients in Bakersfield and Kern County, ensuring that their rights are protected and their interests are represented with the highest level of professional care. If you are facing a payroll audit or have questions about your tax liability, contact our office to discuss your options.